Whether GLP-1 is covered by insurance depends heavily on your specific plan, diagnosis, and employer benefits. This guide explains how GLP-1 insurance coverage typically works, what affects approval, and what to do if your plan doesn't cover treatment.
What Are GLP-1 Medications?
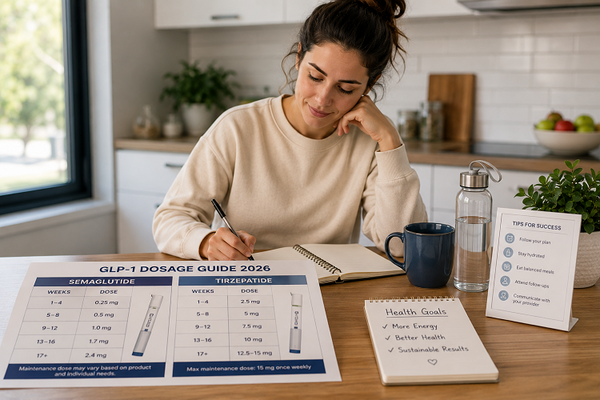
GLP-1 medications, including semaglutide and tirzepatide, are prescribed for type 2 diabetes management and, in some cases, chronic weight management. They work by mimicking a natural hormone that regulates appetite and blood sugar.
Common brand names include Ozempic, Wegovy, Mounjaro, and Zepbound. Each is approved for specific medical uses, which directly affects whether insurance for semaglutide or insurance for tirzepatide applies to a given prescription.
Understanding the approved use behind your prescription is often the first step in understanding your coverage.
Does Insurance Cover GLP-1 Medications?
Whether GLP-1 is covered by insurance varies significantly by plan, employer, and diagnosis. Some plans cover these medications for type 2 diabetes but exclude them entirely for weight loss, even when prescribed by a licensed provider.
Semaglutide insurance coverage and tirzepatide insurance coverage are not guaranteed, even among plans from the same insurer. Employer-sponsored plans, in particular, can choose whether to include GLP-1 medications in their formulary.
Because coverage varies so widely, patients should verify benefits directly with their insurance provider rather than assuming coverage based on general information.
Coverage for Weight Loss vs. Type 2 Diabetes
Insurance plans are generally more likely to cover GLP-1 medications for type 2 diabetes than for weight loss alone. This is because diabetes management has long been an established, reimbursed medical use.
Weight loss medication insurance coverage remains inconsistent, with many plans requiring additional documentation or excluding weight-loss indications entirely, regardless of medical necessity determined by a provider.
Patients should ask their insurer specifically whether coverage differs based on diagnosis code, since the same medication may be treated differently depending on the reason it's prescribed.
Which Insurance Plans May Provide Coverage
Coverage patterns differ across plan types. Some employer-sponsored plans include GLP-1 coverage for weight loss, while others have specifically excluded it in recent years. Medicare has also introduced limited, temporary coverage pathways for certain beneficiaries in 2026.
Medicaid coverage varies by state, with some programs covering GLP-1 medications for diabetes but not weight loss. Marketplace plans similarly differ based on state regulations and individual insurer policies.
Because these patterns shift over time, confirming current benefits directly with your plan is the only reliable way to know your coverage status.
Prior Authorization and Eligibility Requirements
Most insurers require documentation before approving GLP-1 medications:
- Prior authorization from a licensed healthcare provider
- Confirmation of diagnosis, such as type 2 diabetes or a qualifying BMI
- Evidence of prior weight-loss attempts, in some cases
- Documentation of weight-related health conditions
- Renewal requirements for continued coverage
Prior authorization GLP-1 requirements can delay access, so working with a provider experienced in submitting thorough documentation may help streamline the process.
What to Do If Insurance Denies Coverage
If your claim is denied, consider these steps:
- Request a written explanation of the denial reason
- Ask your provider about submitting an appeal with additional documentation
- Confirm whether a different diagnosis code applies to your situation
- Explore manufacturer savings programs, if eligible
- Discuss alternative treatment options with your clinician
A denial is not always final, and many patients successfully appeal with proper medical documentation supporting necessity.
Options for Patients Without Insurance
Patients dealing with GLP-1 without insurance still have legitimate paths to treatment. Manufacturer cash-pay programs, compounded formulations through licensed pharmacies, and telehealth programs offering physician-supervised weight loss are common options.
These paths still require a prescription and proper medical evaluation. Comparing total costs, including consultations and follow-up care, helps patients make informed decisions when paying out of pocket.
Why Physician Documentation Matters: Final Guidance and Next Steps
Thorough physician documentation often plays a central role in insurance approval. Clear records of diagnosis, prior treatments, and medical necessity give insurers the information needed to evaluate coverage requests accurately.
When exploring whether GLP-1 is covered by insurance, remember that approval is never guaranteed and depends on your specific plan and circumstances. Verifying benefits directly with your insurer remains the most reliable step.
Treatment decisions, whether covered by insurance or paid out of pocket, should always be made in partnership with a licensed healthcare provider who can guide you safely.
Frequently Asked Questions
Does insurance cover GLP-1 medications for weight loss? Coverage varies by plan and employer. Some insurers cover GLP-1 medications for weight loss, while others limit coverage to type 2 diabetes. Checking directly with your insurance provider is the best way to confirm your specific benefits.
What is prior authorization for GLP-1 medications? Prior authorization is a process where your insurer requires documentation from your provider confirming medical necessity before approving coverage. Requirements vary by plan and diagnosis.
What if I don't have insurance coverage for GLP-1 medications? Patients without coverage can explore manufacturer savings programs, compounded formulations through licensed pharmacies, or telehealth programs offering physician-supervised care, always with a valid prescription.
Speak with a licensed clinician and verify your benefits directly with your insurance provider to understand your GLP-1 coverage options. A qualified provider can help you explore physician-supervised treatment paths that fit your medical needs and financial situation.